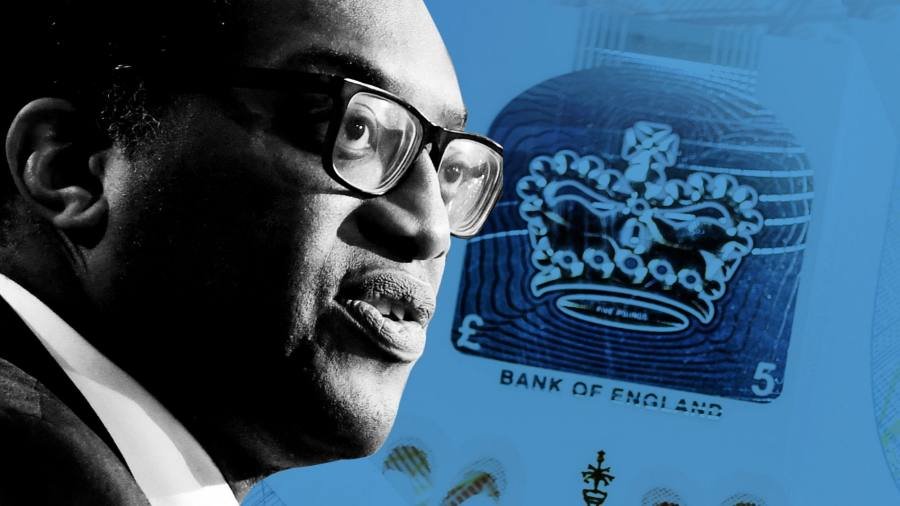
The prospect of a shift in the UK government’s fiscal plans gave another big boost to gilt markets on Friday, as Prime Minister Liz Truss sacked chancellor Kwasi Kwarteng and prepared a dramatic U-turn on the fiscal plans that sent bond markets into a tailspin last month.
The 30-year gilt yield fell 0.17 percentage points to 4.37 per cent. Earlier this week long-term borrowing costs had climbed above 5 per cent, reaching levels that had prompted the Bank of England to launch its emergency bond-buying programme on September 28.
While a bigger volume of purchases by the central bank over the past two days had helped to stabilise markets, expectations of a reversal of some of Kwarteng’s £43bn of unfunded tax cuts added fuel to the rally. Traders and investors said there were also hopes that the government’s broader economic strategy of borrowing in a bid to boost growth at a time of high inflation had been discredited.
“For the market there was a perception this week that things had got so bad they can only improve,” said Mohammed Kazmi, a portfolio manager at Union Bancaire Privée. “Either there’s a big U-turn on tax cuts or you get pressure for a new cabinet and leader. There’s a Conservative party that can still push out the PM. The market likes that those institutional frameworks still exist.”
Ten-year gilt yields also fell sharply, reflecting a surge in prices, trading 0.21 percentage points lower at 3.98 per cent. Sterling fell 1.2 per cent to trade at $1.1198 against the dollar, giving up part of Thursday’s big rally.
The BoE was forced to step up its intervention in gilt markets this week as a sell-off initially sparked by Kwarteng’s borrowing plans reignited. The central bank doubled the size of its daily purchases on Monday and broadened them to include inflation-linked gilts on Tuesday.
However, the BoE has also repeatedly insisted that the buying will not be continued beyond Friday’s deadline, with governor Andrew Bailey saying on Tuesday that pension funds that have been plunged into crisis by the rise in gilt yields had just three days to sell whatever assets they need to in order to replenish their cash buffers.
The pace of BoE buying increased with a total of £9.1bn of bonds purchased on Wednesday and Thursday. Even so, with one day remaining the facility has only bought £17.8bn of a potential £65bn of debt.
Source: Financial Times