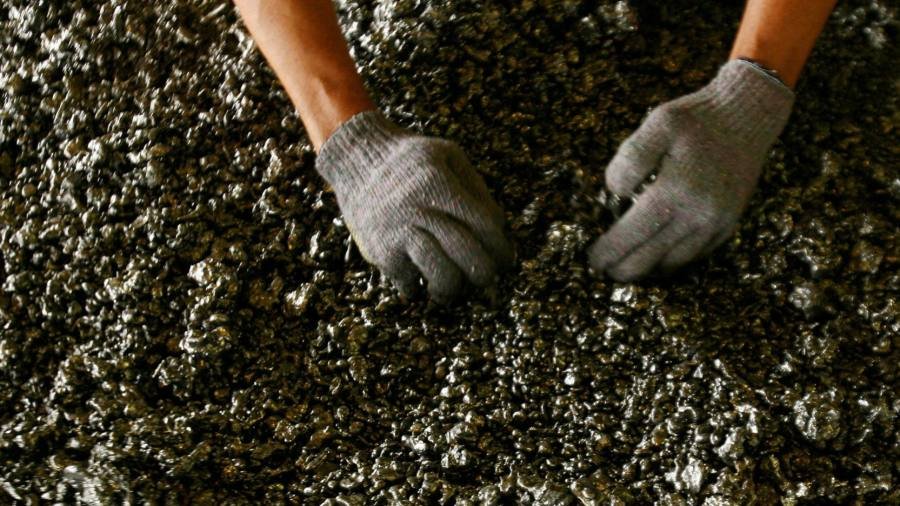
Nickel reduces corrosion. The metal has had the opposite effect on the reputation of the London Metal Exchange, owned by Hong Kong Exchanges and Clearing. A report by Oliver Wyman attempts to explain what happened in a spectacular short squeeze last March.
The consultancy sidesteps one crucial element in all the chaos: the decision by the LME to cancel some big purchases of nickel. This helped beleaguered short sellers, apparently including Chinese metals tycoon Xiang Guangda.
The cancellations shook investors’ confidence in the London nickel market as much as unprecedented price swings.
Oliver Wyman has, however, pointed to other failings of the report sponsor. It says the LME did not know enough about the size of short positions. These theoretically have unlimited risk. Monitoring their size is an important job for any exchange and clearing operation, in this case LME Clear, another subsidiary of HKEX.
Even before Russia’s invasion of Ukraine, reports had surfaced about a large short held by one trader, later revealed to be Xiang. The LME was aware of the amount of open trades on its exchange. But it apparently knew little about over-the-counter (off-exchange) trades, which equalled a third of LME volumes. That left another blind spot in its oversight.
Exchanges try to prevent buyers from cornering the market in any asset, as Italy’s Ferruzzi tried to do with soyabeans in 1989.
The limited data available to the LME and LME Clear meant they were unable to foresee the scale of the short squeeze when they demanded more cash margin from traders during early March. When the LME suspended its margin calls on March 7 as nickel prices soared, the move contributed to fears the system was broken. The nickel futures contract price doubled to more than $100,000 a tonne the next day.
UK regulations require real-time monitoring of margins. Oliver Wyman says the LME stopped doing so for more than five hours on March 8.
It is disappointing, if perhaps inevitable, that this report withheld comment on the subject most challenging to LME and HKEX. However, it points investigations by the Financial Conduct Authority and the Bank of England in the right direction.
LME lacked the data needed to supervise the nickel market adequately. Decision-making was poorly informed. The FCA must now probe the motivation for some of those decisions, notably trade cancellations.
Source: Financial Times